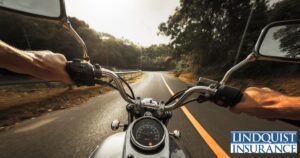
Nothing beats riding a motorcycle. The open road, the freedom, and the feeling of being connected to the ride are a big part of why people love motorcycles in the first place.
But that freedom also comes with responsibility. Accidents happen, even to experienced riders. And when you are involved in an accident that is determined to be your fault, one of the most important questions becomes: Will your motorcycle insurance protect you?
The answer depends on the coverage you carry.
What Happens If You’re at Fault?
Motorcycle liability insurance is designed to help protect you financially when you are responsible for an accident that injures someone else or damages their property.
For example, imagine you are riding through an intersection and misjudge the distance between your motorcycle and another vehicle. You collide with the car, damaging its bumper and causing injuries to the other driver.
If you are found at fault, the other party may have a claim against you for their covered losses. Your liability insurance can help pay for covered bodily injury and property damage, up to the limits of your policy.
The Maryland Insurance Administration states that motorcycle insurance provides liability coverage when you are involved in a loss and found to be at fault for damaging someone else’s property or injuring another person. Maryland also requires liability insurance to register a motorcycle and obtain tags. ***
That is why having motorcycle insurance is about more than simply meeting a legal requirement. It is about protecting your financial future when something goes wrong.
Liability Coverage Does Not Automatically Pay for Your Motorcycle
Here is where motorcycle insurance can get confusing.
If you cause an accident, your liability coverage is generally designed to protect you against covered claims made by other people. It does not necessarily mean your own motorcycle will be repaired or replaced after an accident that you caused.
That is where additional coverage can become important.
Collision coverage may help pay for damage to your motorcycle resulting from a covered accident, subject to your deductible and policy terms. Comprehensive coverage can protect against certain non-collision losses, such as theft or other covered damage. Motorcycle policies can also include coverage for equipment and customization, as well as roadside assistance.
This matters because motorcycles are often customized. Saddlebags, upgraded exhaust systems, custom paint, electronics, aftermarket wheels, and other accessories can add significant value to a bike. You do not want to assume those additions are automatically covered without checking your policy.
How Much Coverage Do You Need?
Maryland requires motorcycle owners to carry minimum liability limits of $30,000 per person, $60,000 per occurrence for bodily injury, and $15,000 for property damage. The state also requires at least those minimum limits for uninsured motorist bodily injury and property damage coverage. Higher limits are available.
The important question, however, is not simply, “What is the minimum amount I can legally carry?” A better question is, “How much protection makes sense for me?”
Consider what you own, how much you ride, the value of your motorcycle, whether you have other assets to protect, and how much financial risk you are comfortable taking.
Minimum coverage can satisfy the law, but it may not provide the level of protection you want if a serious accident occurs.
What if the Other Driver Is at Fault?
Being a responsible rider does not mean every accident will be your fault.
Another driver may fail to yield, turn in front of you, follow too closely, or cause an accident because they are distracted. That is one reason uninsured and underinsured motorist coverage deserves attention.
If the at-fault driver does not have enough insurance or has no insurance at all. Your own coverage may provide an important layer of protection, depending on the circumstances and terms of your policy. It is worth reviewing this coverage before an accident rather than discovering its limitations afterward.
Motorcycle Insurance Should Fit the Way You Ride
Not every motorcycle owner has the same needs.
You may ride your bike every day. It may come out of the garage only on warm weekends. You may have a touring motorcycle and take long trips. Or perhaps you own a heavily customized bike that represents years of work and investment.
Your insurance should take those factors into account.
The Maryland Insurance Administration points out that the cost of motorcycle insurance can vary based on numerous factors and recommends talking with an insurance producer or insurer to determine what coverage best fits your needs.
Don’t Wait Until After an Accident to Check Your Policy
An accident is a bad time to discover that you do not have enough coverage.
Take a few minutes to review your motorcycle policy. Know your liability limits. Understand your deductible. Ask whether your accessories and custom equipment are covered. Review your uninsured and underinsured motorist coverage. If you financed your motorcycle, make sure you understand any coverage requirements from your lender.
Most importantly, talk with an insurance professional who can help you understand what your policy actually does—and does not—cover.
At Lindquist Insurance, we can help you take a closer look at your motorcycle insurance needs and explore coverage options designed around the way you ride.
Before you hit the road, make sure your insurance is ready for the ride too. Contact Lindquist Insurance today to review your motorcycle coverage and get started on a policy that gives you greater confidence every time you ride. Call (301) 694-0008 for a free motorcycle insurance quote.
We serve the Annapolis, MD and the Frederick, MD area.
*** You can also review the state’s consumer guidance on motorcycle insurance in Maryland for additional information about required coverage and available options.